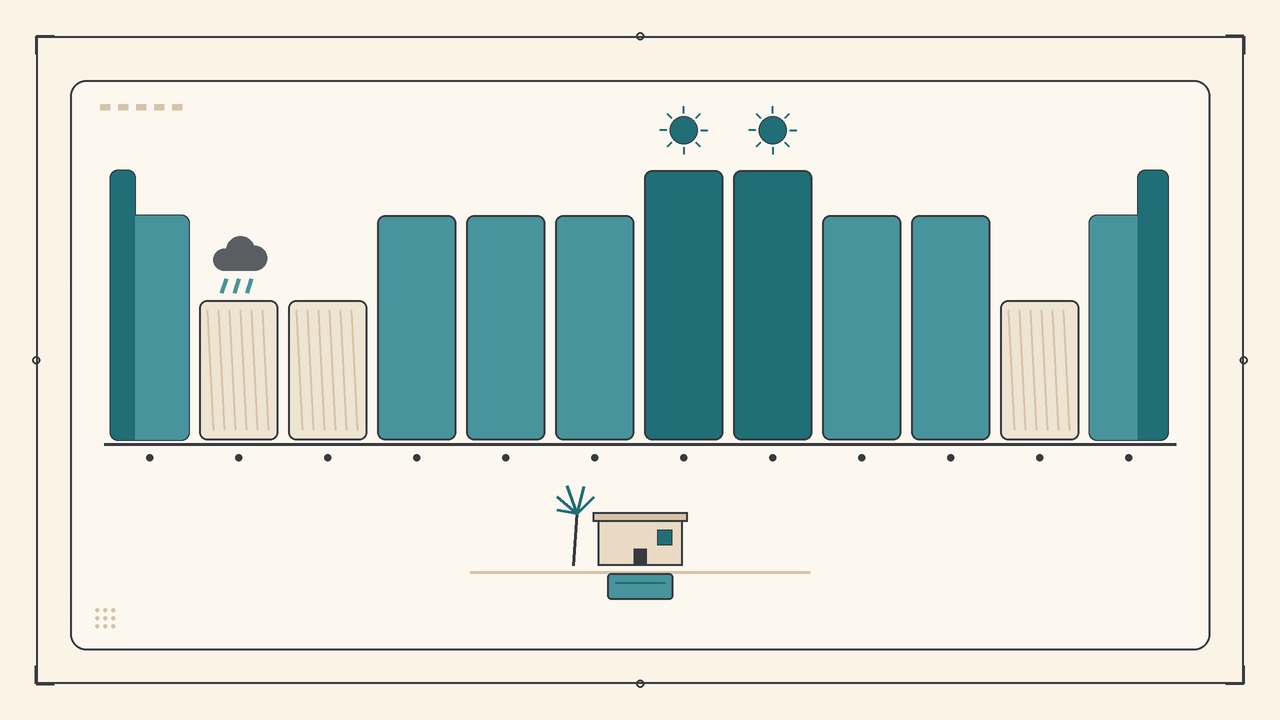
Bali has two high seasons for villa rentals: July–August and the Christmas–New Year window (about 20 December to 8 January). Shoulder season covers April–June and September–October, and low season falls in February–March and November. In Solar Property's historical 2025 data for managed 2–4 bedroom villas, occupancy ran from 42–58% in February to 88–96% in July, and peak nightly rates sat 35–65% above the annual baseline. If you are pricing a villa, planning a purchase or checking a seller's revenue claims, those swings matter more than any single "average occupancy" number.
Quick answer by season
| Season | Months | Typical villa occupancy | Nightly rate vs baseline |
|---|---|---|---|
| High (peak) | July–August, ~20 Dec – 8 Jan | 82–96% | +35–65% |
| Shoulder | April–June, September–October | 62–82% | −15% to +20% |
| Low | February–March, November | 42–65% | −10% to −35% |
Ranges are historical benchmarks for managed villas in Canggu, Seminyak and Ubud, not a forecast or a guarantee for any specific property.
Research note: the figures come from historical Solar Property portfolio data recorded before the management handover to Vsemdom on 1 June 2026, cross-checked with public demand signals such as BPS Bali tourism releases and AirDNA Bali market data. This page is investor research, not an offer to operate or manage villas.
Investor next step: if you are comparing villas to buy, use the Bali villa investment research page and the live properties for sale board, and ask every seller for occupancy broken down by month, not just an annual figure.
What this guide covers (and where to go deeper)
This page is the year-round calendar: which months are strong, which are weak, and how that feeds an annual revenue estimate. Deeper tactics live in dedicated guides, so we keep them short here:
- Peak-month tactics: July–August peak season revenue guide
- Filling the quiet months: low season occupancy strategy
- Rate setting: Bali villa pricing strategy 2026
- Ownership, ROI and buying: Bali villa investment guide, PT PMA villa ownership guide, buy villa in Bali 2026
Just looking for a place to stay on your travel dates? The Bali villa rental page is the better starting point.
Month-by-month villa occupancy and rates in Bali
The table below shows the historical 2025 benchmark for managed 2–4 bedroom villas in Canggu, Seminyak and Ubud, based on the Solar Property portfolio and AirDNA Bali market data.
| Month | Occupancy | Rate vs baseline | Season | What it means for an owner |
|---|---|---|---|---|
| January | 68–80% | +10–25% | High → shoulder | Holiday premium in week one, then demand eases |
| February | 42–58% | −25–35% | Low | Wettest month; the statistical low point of the year |
| March | 48–62% | −20–30% | Low → shoulder | Nyepi (usually March) closes the island for a day; monthly stays help |
| April | 62–72% | −5–15% | Shoulder | Recovery begins; finalise July–August pricing now |
| May | 65–75% | Baseline | Shoulder | Solid volume, longer stays, lower turnover cost |
| June | 72–82% | +10–20% | Shoulder → high | Pre-peak; European bookings for summer lock in |
| July | 88–96% | +45–65% | Peak high | Strongest month; 5–7 night minimums are common |
| August | 85–94% | +40–60% | Peak high | Near-full calendars on well-listed villas |
| September | 70–80% | +5–15% | Shoulder | Remote workers extend the season |
| October | 68–78% | Baseline | Shoulder | Steady; direct-booking discounts pay off |
| November | 52–65% | −10–20% | Low | Gap between shoulder and the December ramp-up |
| December | 82–93% | +35–65% | Peak high | Highest nightly rates of the year from ~20 Dec |
Averaged month by month, the table works out to about 72% annual occupancy for a professionally managed villa (67–78% between the low and high ends of the ranges), which is also what the revenue example below implies. Owner-operated villas without active listing management have historically run 50–60%, with the biggest gap in low season.
High season: July–August and Christmas to New Year
The summer peak (July–August) is the stronger of the two. European and Australian school holidays overlap, giving 8–10 weeks of sustained demand. Well-listed villas in Canggu and Seminyak reached 85–96% occupancy through this window and were often booked six weeks ahead.
The Christmas–New Year peak runs from about 20 December to 8 January. It is shorter (around three weeks) but produces the highest nightly rates of the year, typically 35–65% above baseline. Premium listings reached 85–92% occupancy; budget villas ran slightly lower because more supply competes at that price point.
What high season looks like in practice:
- Booking window: 6–10 weeks ahead for summer, 8–12 weeks for Christmas and New Year.
- Minimum stays: most villas enforce 5–7 nights, which lifts revenue per booking and cuts turnover costs.
- Rate premium: 35–65% above the annual baseline nightly rate.
- Conversion: the highest of the year, because peak guests have already decided to travel.
The planning lesson from 2025: July–August pricing should be set by March, April at the latest. Villas that priced summer late left revenue on the table, because the best-converting advance bookings had already gone to listings with rates live early. Peak-week tactics are covered in the July–August revenue guide.
Shoulder season: April–June and September–October
Shoulder season is Bali's most underestimated revenue window. Managed villas held 62–82% occupancy in these months: less than peak, but with reasonable rates and noticeably less operational pressure.
The guest mix shifts towards couples and remote workers. Average stays grow from about 5–6 nights in peak (set by the minimum stay) to 7–10 nights, which reduces cleaning and coordination costs. For a 3-bedroom Canggu villa with a $450 baseline, one direct 10-night stay at $380 a night ($3,800) comes close to five 2-night OTA stays at $480 ($4,800 gross, about $3,900–4,100 after a 15–18% commission), before you count four extra cleanings and check-ins.
September–October 2025 showed a structural shift: occupancy in the Solar Property portfolio stayed above 72% through October, about 8–12 percentage points higher than the same period in 2023, driven by remote-work demand. Villas set up for longer working stays (reliable internet, a proper desk, flexible weekly pricing) captured most of it.
Shoulder months are also where direct bookings earn their keep. Guests staying 7+ nights respond to a small direct discount (5–8% below the OTA rate): the owner avoids a 15–18% platform commission, and the guest saves $25–40 a night.
Low season: February–March and November
Low season has two windows: February–March, after the January holidays, and November, between the October shoulder and the December ramp-up. Unmanaged villas can drop below 40% occupancy, while managed villas with active pricing averaged 50–62%.
February is the low point. It is Bali's wettest month, international arrivals fall across all accommodation types, and nightly rates typically sit 25–35% below baseline. The guest mix moves towards longer, budget-conscious stays, wellness retreats and domestic Indonesian travellers.
Three levers separated strong villas from weak ones:
- Monthly and weekly packages. Monthly rates of roughly $3,000–6,000 for 2–4 bedroom villas attract remote workers. The test is simple: a monthly let wins when it beats the nightly calendar. A villa at $180 a night and 55% occupancy grosses about $2,970 a month, so a monthly let above roughly $3,000 already comes out ahead, with no turnover cleaning or OTA commission on top. Just make sure monthly stays end by late May so they don't block July.
- Wellness and retreat groups. Ubud villas with a yoga shala or a large pool deck attract retreat organisers booking 5–10 days exclusively, and this demand barely reacts to rain.
- Domestic travellers. Indonesian guests are the fastest-growing low-season segment. Listing on Traveloka and Agoda and dropping the minimum stay to two nights in February–March noticeably lifts occupancy — and many foreign-owned villas still aren't listed there.
The full playbook is in the low season occupancy strategy guide. Whether a long-term let beats nightly rentals across the whole year is compared in short-term vs long-term rental.
What seasonality does to a villa's annual revenue
The most common underwriting mistake is annualising peak performance. The example villa below grosses about $17,900 in August (31 nights at $640 and 90% occupancy). Multiply that by twelve and you get $214,000, while its real year comes to about $123,800. Here is a worked historical example for a managed 3-bedroom villa in Canggu with a $450 baseline nightly rate:
| Period | Weeks | Avg nightly rate | Occupancy | Gross (approx.) |
|---|---|---|---|---|
| Peak | 14 | $640 | 90% | ~$56,400 |
| Shoulder | 22 | $430 | 72% | ~$47,700 |
| Low | 16 | $320 | 55% | ~$19,700 |
| Year | 52 | ~$123,800 |
The week counts are rounded blocks carried over from the original model, not exact calendar dates.
After management fees (15–20%), OTA commissions (15–18%) and operating costs (cleaning, maintenance, utilities, property tax), net to the owner typically landed at 55–65% of gross, or roughly $68,000–80,500 in this example. On a $950,000 purchase price, that is about 13% gross and 7.2–8.5% net yield.
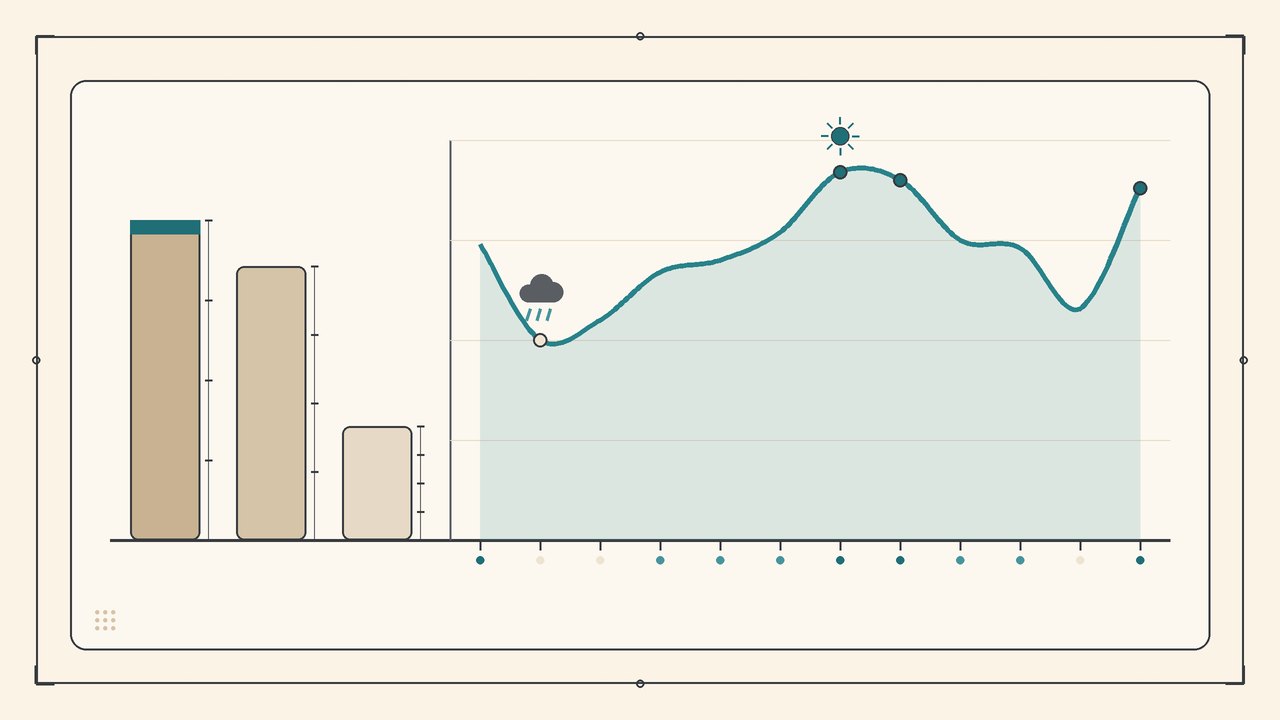
Treat this as an illustration of how the seasons stack up, not a projection for any listing. Your own model should use the villa's actual monthly occupancy, its real cost base and its lease terms. For net ROI bands, payback and leasehold extension risk, continue with the Bali villa investment guide and Bali villa ROI and payback math; for the tax side, see the rental income tax guide.
Seasonal rate tiers in one view
Yuriy Solar, founder of Solar Property Bali: "Most villa owners set a single rate and watch it not work. The properties generating 14–16% gross yield run dynamic pricing with 4–6 distinct rate tiers across the year — not guessing, adjusting based on forward demand data each week."
A simple tier framework for a 3-bedroom Canggu villa at a $450 baseline:
| Tier | Dates | Nightly rate | Minimum stay |
|---|---|---|---|
| Peak | Jul–Aug, ~20 Dec – 8 Jan | $640–720 | 5 nights |
| Pre-peak | June, 1–19 Dec | $520–580 | 3 nights |
| Shoulder | Apr–May, Sep–Oct | $400–480 | 2 nights |
| Low | Feb–Mar, November | $295–360 (or $3,500–4,500/month) | 2 nights |
On top of the tiers, rates should move with the booking window (cut 15–20% on unsold low-season dates close to arrival; raise July if it fills early in April) and with local events such as Nyepi, the BaliSpirit Festival and major Uluwatu surf events. In the historical portfolio, algorithmic base pricing plus a weekly manual review outperformed pure automation by about 8–12% in annual revenue. Detailed rate setting is covered in the pricing strategy guide.
Where bookings come from in each season
Channel mix changes with the calendar. Historical Solar Property Canggu data (2025):
| Period | Airbnb | Booking.com | Traveloka | Direct | Other |
|---|---|---|---|---|---|
| July–August | 65% | 22% | — | 10% | 3% |
| October–November | 45% | 28% | 15% | 12% | — |
| February–March | 40% | 22% | 25% | 13% | — |
Airbnb dominates Western peak demand, Booking.com is strongest with European guests in shoulder months, and Traveloka carries the domestic market that keeps low season alive. For listing-level detail, see OTA channel optimisation.
Bali hotel occupancy vs villa occupancy: using BPS data
The BPS hotel occupancy rate (TPK) is a useful signal of the island's overall demand cycle, but it should not be copied into a villa model. BPS measures hotel rooms; villa occupancy depends much more on area, bedroom count, OTA ranking, reviews, direct-booking share and pricing.
For reference, BPS Bali reported star-rated hotel room occupancy of 55.44% in February 2026, down from 56.67% in January 2026 — the same February dip the villa table shows, in a milder form.
How to read the two together:
- Hotel TPK rising, comparable villa flat: the problem is usually the listing — pricing, photos, reviews or minimum-stay rules.
- Both softening at once: it is most likely market-wide seasonality, so the answer is low-season packages and a broader channel mix, not assuming the villa is broken.
How to use the season calendar before you buy a villa
For a buyer, seasonality is a due-diligence tool. Before trusting any projected yield:
- Ask for 12–24 months of occupancy and ADR by month, not one annual average. A villa at 90% in July and 30% in February is being listed, not managed.
- Check how the pro forma treats low season. If February looks like August, the model is annualising peak.
- Separate management gaps from market gaps. Weak low-season numbers caused by static pricing or missing channels are fixable; a poor micro-location is not.
- Confirm the legal basis for renting. Rental use rights in the lease, licences and the ownership structure all decide whether seasonal income is actually yours — see PT PMA villa ownership and the villas for sale due-diligence checklist.
- Compare areas on their quiet months. Canggu has historically been the most stable year-round; Seminyak and Uluwatu drop harder in February–March. The Canggu vs Seminyak vs Ubud vs Sanur comparison goes area by area.
When you have a shortlist, run it against the properties for sale board and the investment research page. If you are buying a home rather than a rental asset, buy house in Bali 2026 covers that path.
Frequently asked questions
When is high season in Bali for villa rentals?
High season is July–August and the Christmas–New Year window (about 20 December to 8 January). In historical 2025 data for managed villas, July reached 88–96% occupancy and December 82–93%, with nightly rates 35–65% above the annual baseline.
What are the low season months in Bali?
February–March and November. February is the wettest month and the low point of the year: managed villas historically ran 42–58% occupancy, with nightly rates 25–35% below baseline.
What annual occupancy rate should I expect for a Bali villa?
A professionally managed 2–4 bedroom villa in Canggu, Seminyak or Ubud has historically averaged about 72% across the year, within a 67–78% range. Owner-operated villas without active listing management have run closer to 50–60%. Treat these as benchmarks, not a promise for any specific property.
How much do Bali villa rates drop in low season?
February–March rates typically sit 20–35% below the annual baseline. For a villa with a $450 baseline, that means roughly $295–360 a night. Monthly packages of about $3,000–6,000 for remote workers help offset the lower nightly rate.
Is shoulder season worth it for villa owners?
Yes. April–June and September–October historically delivered 62–82% occupancy with longer stays of 7–10 nights, which lowers cleaning and turnover costs. In 2025, remote-work demand kept occupancy above 72% through October.
Which Bali area has the most stable year-round occupancy?
Canggu has historically been the most stable, especially for 2–3 bedroom villas aimed at remote workers. Beach-focused Seminyak and Uluwatu see sharper February–March drops, while Ubud villas with yoga or retreat space hold steady low-season demand.
Can I use Bali hotel occupancy data to estimate villa occupancy?
Only as a demand signal. BPS hotel occupancy (TPK) shows the island-wide cycle — for example, 55.44% for star-rated hotels in February 2026 — but villa occupancy depends on area, size, reviews, pricing and channel mix. Use it to tell a market-wide dip from a listing problem.
Planning a Bali villa purchase around the seasons?
Share the area, bedroom count and the seller's monthly occupancy figures, and pressure-test the revenue story before you commit.